Behind on Bookkeeping? What to Send Your Accountant to Get Caught Up
You know your bookkeeping needs attention. But before you can hand it over, another question comes up: what does your accountant actually need?
If your records are spread across email, bank accounts, spreadsheets, and a box of receipts, getting started can feel like a project on its own. You do not need to make everything perfect before asking for help. A clear starting point is enough.
This catch-up bookkeeping checklist explains what Canadian business owners can gather, how to organize it, and what to do when something is missing.
Start With the Period You Need to Catch Up
Tell your accountant the last month or year you believe was completed, which accounting software you use, and whether you have received any outstanding requests or notices. If you are unsure where the previous work ended, say so. Your accountant can review the records and help establish the starting point.
Also explain what you need from the project: updated books, support for overdue filings, reliable financial reports, or an ongoing monthly service. Agreeing on the scope early helps avoid confusion later.
For example, “my taxes were filed for 2023” does not necessarily tell your new accountant whether the bookkeeping was completed through December 2023 or whether adjustments were entered afterward. Provide the latest completed financial statements and any year-end adjusting entries you have. This helps establish opening balances and reduces the chance of repeating work.
If you operate more than one company, identify which accounts belong to each business. Explain any name changes, new payment processors, closed accounts, or changes in ownership during the catch-up period. A short written overview can save several rounds of questions.
1. Bank and Credit Card Statements
Gather complete statements for every account used by the business during the outstanding period, including accounts that have since closed. Include business credit cards, savings accounts, lines of credit, and payment accounts where relevant.
PDF statements show opening and closing balances. Transaction exports can help with processing, so ask whether your accountant would like both. If personal accounts were used for business purchases, flag those transactions and ask how to share the relevant records.
Check that each month is included and that the statements show every page. A screenshot of recent transactions may leave out balances, older activity, or important account details. Download records from closed accounts as soon as possible, since retrieving them later may involve extra steps or bank fees.
Reconciliation means comparing the bookkeeping to the account statements and investigating differences. A transfer from your chequing account to your savings account should be matched on both sides, for instance, rather than counted as an expense in one account and revenue in the other. The CRA’s guide to business records explains why supporting documents matter beyond the totals in your accounting software.
2. Sales Invoices and Payment Processor Reports
Provide sales invoices, customer payment records, and reports from any point-of-sale system, online store, or payment processor you use. Include refunds, chargebacks, and processing fees.
A bank deposit may represent several customer payments after fees or refunds have been deducted. The supporting reports help your bookkeeper understand how that deposit was calculated instead of treating every deposit as a new sale.
Consider a simple example: a processor collects $1,000 from customers, deducts $30 in fees, and deposits $970. Recording only the deposit can hide both the original collections and the processing cost. Sales reports help identify the sale, applicable taxes, fees, and any refunds separately. The correct entries still depend on the underlying transactions.
Include a list of customer invoices that remained unpaid at the end of each year, along with customer deposits and credit notes. If you accept cash, provide cash-sales records and explain whether cash was deposited, kept on hand, or used for business purchases.
3. Receipts, Supplier Bills, and Expense Records
Collect supplier invoices and receipts for business purchases. Where the purpose is unclear, add a brief note explaining what the purchase was for. Include unpaid supplier bills as well as amounts already paid.
Do not assume that every payment from a business account is a business expense. Identify personal purchases, transfers between accounts, and amounts paid on behalf of another business so your accountant can review them correctly.
For mixed-use costs such as a vehicle or cellphone, explain how the item was used and provide any supporting usage records you maintain. Your accountant can assess the appropriate treatment; paying through a business account does not establish that the entire amount qualifies.
GST/HST documentation deserves particular attention. Eligible registrants may recover qualifying GST/HST through input tax credits, subject to the applicable conditions. The CRA requires sufficient supporting evidence before a claim is made, and invoice requirements vary with the amount. Keep the detailed supplier invoice rather than relying only on the card payment. See the CRA’s input tax credit eligibility and supporting-document requirements.
4. Payroll and Contractor Records
If you have employees, gather payroll summaries, pay-run reports, remittance records, and year-end slips already prepared. Include records from any payroll provider you used during the period.
For contractors, provide invoices and payment details. If you are unsure how a worker has been recorded, raise the question rather than changing their classification yourself.
Net amounts deposited into employees’ bank accounts do not explain gross wages, deductions, or employer contributions. Payroll reports help your accountant compare the amounts processed, paid, and remitted, and identify questions that need follow-up.
The CRA’s GST/HST and payroll record-keeping guidance identifies payroll information to retain, including employee hours, amounts withheld, TD1 forms, and information slips and returns. Ask your accountant which records are needed for the specific periods being reviewed.
5. Previous Accounting Records and CRA Correspondence
Share existing bookkeeping files, financial statements, previously filed returns, and relevant correspondence from your previous accountant. Include GST/HST records where applicable, along with CRA notices or requests that relate to the work.
Tell your accountant about any response dates shown on a notice at the outset. Organizing the books and responding to a specific request may need to be coordinated.
Provide complete copies of notices, including the tax period, account type, requested information, and response date. A notice of assessment, a request for supporting documents, and a demand to file serve different purposes. Do not assume that completing the bookkeeping alone answers the letter or changes a deadline.
If your accountant needs to deal with the CRA on your behalf, arrange representative authorization separately. Sharing documents does not automatically authorize CRA access. Follow the CRA’s instructions for authorizing a representative and agree on the access needed. Keep your own CRA sign-in credentials private.
6. Loans, Equipment, and Owner Transactions
Provide loan agreements and statements, equipment purchase or sale documents, and details of money you put into or took out of the business. For financed purchases, include the purchase invoice as well as the financing paperwork.
These records help explain transactions that cannot be understood from a bank description alone. A loan repayment, for example, should not simply be treated as an ordinary supplier payment.
A monthly equipment-loan payment can include both principal and interest. The financing statement helps separate those amounts, while the purchase invoice identifies the asset itself. If equipment was sold, traded in, or refinanced, include those documents too.
For owner transactions, add a short explanation: “owner paid supplier personally,” “funds introduced to cover payroll,” or “transfer between related companies.” These notes help your accountant investigate the correct treatment instead of making assumptions from a vague bank description.
How to Organize Your Documents Without Overcomplicating It
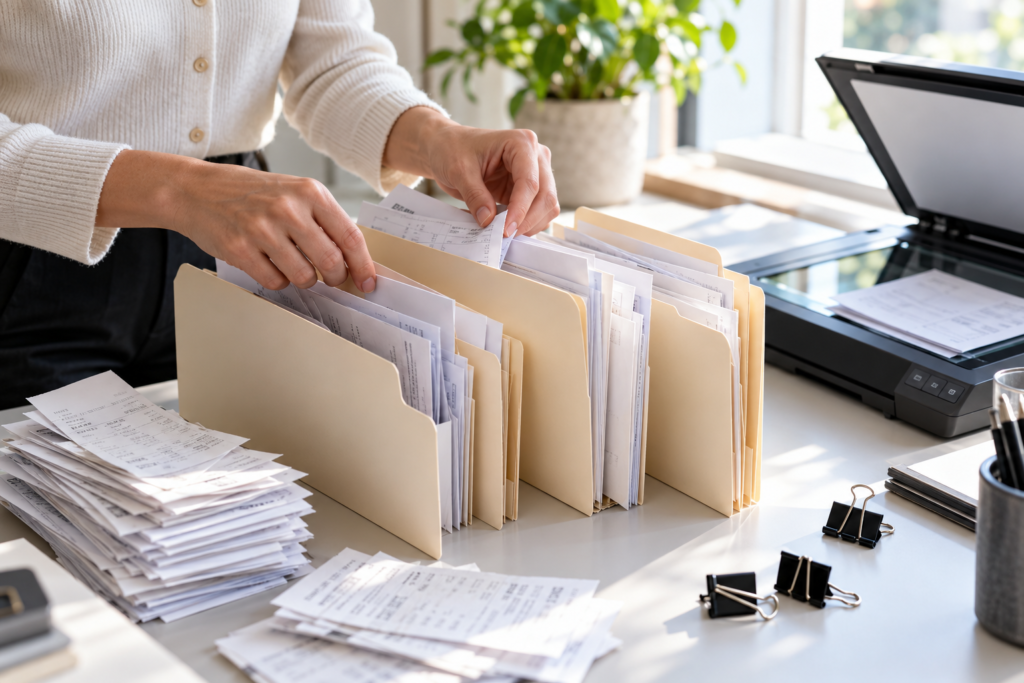
Create a folder for each business, then separate records by year and document type. Simple names such as “2025 – Bank Statements” and “2025 – Sales Reports” are usually more useful than one folder containing hundreds of unnamed files.
Keep the original files and provide a short list of anything missing. Before uploading sensitive records, ask your accountant which secure document-sharing method to use. Arrange access to accounting software through its user-invitation feature rather than sending your own password.
What If Some Records Are Missing?
Start with what you have. Your bank, suppliers, payment processor, or previous accountant may be able to provide replacement records. Make a list of the gaps so the same missing document does not hold up repeated requests.
A bank statement can help identify a payment, but it may not explain the purchase or provide all the supporting detail needed. Let your accountant assess the gaps. Avoid creating receipts or guessing figures to make the records appear complete.
Use a simple missing-records list showing the date, amount, supplier or customer, missing document, and person responsible for obtaining it. This lets work continue on complete sections while outstanding items are tracked. Keep any replacement documents and explanations together so they are easy to review later.
How Long Should You Keep Records After Catching Up?
Finishing the cleanup does not mean the supporting files can be discarded. The CRA generally requires records for six years after the end of the last tax year they relate to. Importantly for overdue filings, records supporting a late-filed income tax return must be kept for six years from the filing date. Other exceptions can require longer retention.
Records relating to long-term property transactions or unresolved objections and appeals can have different retention requirements. Check the CRA’s record-retention rules and exceptions before deleting older files. Ask your accountant to help identify what must remain available.
What Should Happen After the Cleanup?
Before the project ends, ask which accounts were reconciled, which periods were completed, and whether any transactions or documents remain unresolved. Confirm which tax filings were included in the engagement and which still require separate work. Updated books and submitted tax returns are distinct deliverables.
Then agree on a routine you can maintain: how receipts will be collected, when statements will be provided, who will review questions, and when the books will be reconciled. A monthly review of unpaid customer invoices, supplier balances, and unfamiliar transactions can help prevent another backlog.
Will Organized Records Reduce Catch-Up Bookkeeping Costs?
Complete, accessible records can reduce time spent chasing documents and investigating unexplained transactions. The final scope still depends on transaction volume, the number of accounts, the period outstanding, and any corrections required.
For more on pricing, read our Catch Up Bookkeeping Costs Canada Guide. Ask for a clear scope explaining what is included, what you need to provide, and how additional work will be handled.
Need Help Getting Your Books Caught Up?
At Effortless Accounting, we help business owners across Canada organize overdue records and move forward with a clear bookkeeping plan. You do not need to finish the cleanup before speaking with us.
Our catch-up bookkeeping service starts with understanding where things stand and what work is needed. Book a consultation to discuss your records, priorities, and next steps.
Frequently Asked Questions
Do I need every receipt before contacting an accountant?
No. Contact your accountant with the records you have and identify anything missing. They can explain what else is needed and help you prioritize the next steps.
Are bank statements enough for catch-up bookkeeping?
They are an important starting point, but invoices, receipts, payroll reports, and other supporting records may also be needed to explain transactions accurately.
Can I get help if I am several years behind?
Yes. Start by identifying the outstanding years and gathering available records. The scope and timeline will depend on the volume of work, the condition of the records, and how quickly missing information can be obtained.
Should I categorize everything before handing it over?
You can add helpful notes, but ask your accountant before spending hours recategorizing old transactions. Existing entries may need review, and unnecessary changes can create more cleanup.